
Key Takeaways
- Strong sales do not always mean cash is available when bills are due; monitor payment timing and upcoming expenses.
- Use a weekly cash-flow forecast to track income, obligations, and potential shortfalls.
- Build a realistic cash reserve based on operating costs and revenue patterns.
- Compare funding options, including credit lines, term loans, invoice financing, and supplier terms.
- Review interest rates, fees, repayment schedules, collateral, and personal guarantees before borrowing.
- Match financing to a clear business need and ensure repayments fit a conservative cash-flow forecast.
- Improve invoicing, track overdue payments, and review cash flow regularly to reduce reliance on debt.
A business can be profitable on paper and still run short of cash. That can happen when a large customer pays late, payroll arrives before invoices are collected, or a busy season requires inventory and labor before revenue comes in. A business line of credit may help cover a temporary gap, but funding works best when it supports a clear plan rather than replaces one. Cash-flow pressure is not automatically a sign of poor management. It is often a timing issue. The goal is to understand when money enters and leaves the business, build a reasonable reserve, and choose financing only when the repayment plan fits the company’s expected cash flow.
Why Cash Flow Can Feel Tight Even When Sales Are Strong
Profit measures whether revenue exceeds expenses over a period of time. Cash flow tracks whether the business has money available when bills are due. A company may record a sale today but not receive payment for 30, 60, or 90 days. In the meantime, it may still need to pay employees, suppliers, rent, insurance, and taxes. For example, a landscaping company may win a commercial contract in spring, then pay for crews, fuel, and materials for several weeks before the client’s invoice is paid. The work can be worthwhile, yet the timing can create a short-term shortage.
How to Review the Business Cash Cycle
The cash cycle is the time between paying for business needs and collecting money from customers. Reviewing it regularly helps identify shortages before they become urgent.
Track the timing that matters
- Average time customers take to pay invoices.
- Supplier due dates and available payment terms.
- Payroll, rent, debt, software, and insurance payment dates.
- Inventory purchases and seasonal demand changes.
- Accounts receivable that are overdue or concentrated among a few customers.
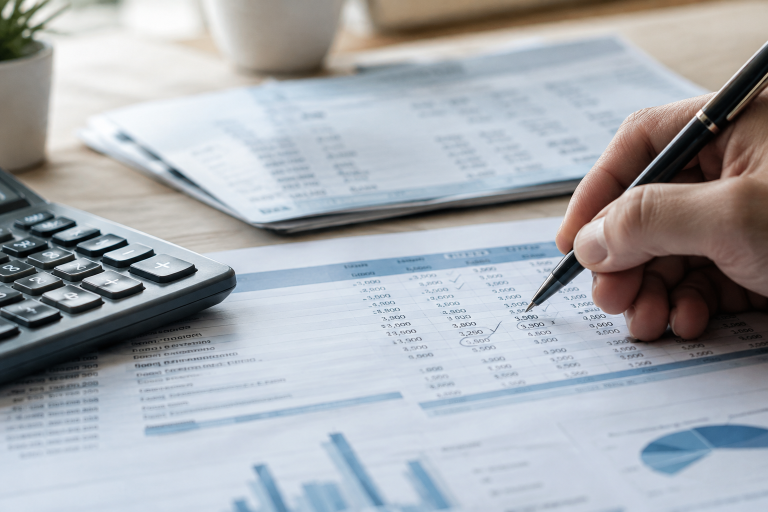
Review at least six months of bank statements, invoices, and bills. Then create a simple weekly forecast showing expected cash in, required cash out, and the estimated ending balance. Update it when a customer delays payment, sales change, or a major expense appears.
How Much Cash Should a Business Keep?
There is no universal reserve target. A firm with predictable contract revenue may need a different cushion than a retailer with seasonal sales. Start by identifying essential monthly costs, then build reserves in stages:
- Cover the next two weeks of essential bills.
- Work toward one month of operating expenses.
- Increase the cushion if revenue is uneven, seasonal, or tied to a small number of clients.
Borrowed money can provide flexibility, but it should not become a substitute for basic cash planning or consistent invoicing.
Short-Term Funding Options to Compare
Funding choices vary in speed, cost, repayment frequency, collateral requirements, and whether a personal guarantee is required. Compare the structure to the need rather than assuming one product is best.
- Business credit cards: May fit small, routine purchases, but balances can become expensive if carried for long periods.
- Revolving credit lines: May fit recurring short-term gaps, such as payroll timing or inventory purchases.
- Short-term loans: May fit a known expense with a defined repayment schedule.
- Invoice financing: May help businesses that have unpaid invoices from creditworthy customers.
- Equipment financing: May fit equipment purchases when the asset itself supports the transaction.
- Supplier terms: May reduce the immediate cash burden by extending the time allowed to pay for inventory or materials.
Some businesses may also explore SBA 7(a) financing for working capital, which can be used for short- and long-term working capital through participating lenders, subject to program and lender requirements.
When a Revolving Credit Line May Fit
A revolving line generally allows a business to draw funds up to an approved limit, repay the amount used, and access available credit again under the terms of the account. That structure can suit seasonal inventory, a brief gap between payroll and customer collections, unexpected repairs, or deposits needed for confirmed work. Flexibility does not mean free access. Review the interest rate, draw fees, maintenance fees, renewal terms, payment frequency, collateral requirements, and personal-guarantee provisions before using a line. A revolving facility may be less appropriate for a purchase that will deliver value over many years.
Credit Line or Term Loan: Which Fits Better?
A credit line is often better suited to repeated, smaller, less predictable needs. A term loan is often better suited to a one-time expense with a known price. For instance, a restaurant purchasing ingredients ahead of a busy season may value flexible access, while a contractor buying a work vehicle may prefer financing aligned with that asset. As a practical rule, try to match the repayment period to the useful life of what is being purchased. Avoid using short-term debt for long-term expenses unless the business can comfortably handle the faster repayment schedule.
How to Prepare Before Applying
Clear records can make lender conversations easier and help the owner compare offers. Gather recent business bank statements, profit and loss statements, balance sheets, tax returns when requested, current debt details, accounts receivable and payable reports, and a short explanation of how funds will be used. Check business and personal credit reports for errors, and request an amount tied to a specific need. Applying for the largest available amount can create unnecessary repayment pressure.
How to Check the Real Cost of Borrowing
The advertised rate is only part of the cost. Ask for the total dollar amount to be repaid, then review origination charges, draw fees, late fees, early repayment rules, automatic-debit terms, collateral requirements, and personal guarantees. A lower monthly payment can still cost more overall if it extends the repayment period. Business owners should also set aside money for taxes as cash comes in. The IRS-outlined business tax responsibilities can help owners identify federal filing and payment obligations to include in their forecasts.
How to Build a Repayment Plan
Test every proposed payment against a conservative forecast, not the best sales month. Ask whether the payment still works during a slow period, whether it competes with payroll or taxes, and what happens if a major customer pays late. Keep a separate record of every draw, fee, and repayment. Be cautious about taking new debt to make payments on older debt. If refinancing or restructuring is being considered, review the full costs and obligations carefully before proceeding.
A Simple Cash-Flow Funding Checklist
- Identify the exact cash-flow gap and its cause.
- Estimate the amount needed and the expected repayment date.
- Consider operational fixes, including faster invoicing or improved supplier terms.
- Compare at least two funding structures.
- Calculate total repayment, fees, guarantees, and collateral obligations.
- Test payments against a slow-month forecast.
- Track draws and repayments, then review the plan monthly.
Final Thoughts
Strong cash-flow planning starts with timing, not panic. When owners understand their cash cycle, maintain reserves, and borrow for a defined purpose, they can make choices that support day-to-day operations without placing unnecessary pressure on future cash flow. This begins with regularly reviewing when customer payments are expected, when bills must be paid, and how much money is available to cover upcoming obligations. Keeping track of payroll, rent, supplier invoices, taxes, and other recurring expenses can help business owners identify potential shortfalls before they disrupt normal operations. Setting aside a realistic reserve also provides room to manage delayed payments, seasonal revenue changes, and unexpected costs. If additional financing is needed, owners should compare available options and consider whether the repayment schedule aligns with expected income. By combining consistent monitoring, practical budgeting, and thoughtful borrowing decisions, small businesses can respond to financial challenges more effectively and maintain a clearer view of their short- and long-term priorities.
